
Chống Gian Lận Tài Chính Với Real-Time Data Platform, white paper thiết yếu spotlight trend gian lận tài chính mới nhất, cách công ty chống lại hiệu quả, và Redis giúp doanh nghiệp đạt mục tiêu. Download miễn phí dưới đây.
Dịch bệnh gian lận là thực và tổ chức tài chính vật vã theo kịp tấn công liên tục và chiến thuật thay đổi của tội phạm mạng. Khi global financial services landscape evolves, gian lận di chuyển cùng chuyển đổi digital banking, tìm cách innovative đánh cắp hoặc giả danh identity khách hàng, và commit fraud.
Kể từ pandemic, ~35% khách hàng retail banking tăng sử dụng online banking (Deloitte, 2020), tạo quantum leap adoption. Thêm vào đó, ~53% dân số thế giới expected dùng digital banking đến 2026 (Juniper Green, 2021).
Khi consumer chuyển sang digital banking, online fraud tăng và tình hình tệ hơn. Survey gần đây highlight 47% business experienced fraud trong vài năm qua (PwC, 2020), cướp đi estimated $42 tỷ.
Ngân hàng và payment processor làm việc chăm chỉ detect fraud trước khi xảy ra nhưng struggle keep up với evolving tactics của tội phạm. Vì họ vẫn phụ thuộc vào static knowledge-based identity validation, rules-based systems, thêm vào slow, siloed systems cho phép fraud xảy ra qua một channel không connect với channel khác.
Rules-only systems detect hiệu quả simple, non-changing, known patterns như validate blacklist hoặc user purchase profile history. Tuy nhiên, struggle distinguish risk từ normal behavior.
Identity theft, account takeover, và rigidity của legacy systems khiến chúng không adapt được evolving real-world scenarios. Ngân hàng và financial services institution cần tận dụng digital identities và chuyển sang multilayer approach增强 rules-based fraud detection bằng complementary mechanisms: AI/ML transaction risk scoring, statistical analysis, anomaly detection.
Machine learning (ML) algorithms và artificial intelligence (AI) predictive models có thể evolve và learn khi analyze và detect fraud dựa trên historical và real-time transactional information. Tuy nhiên, do size và complexity của data pipelines, successful implementation AI/ML không chỉ phụ thuộc accurate models mà còn performance và resiliency của surrounding data infrastructure.
Transaction Fraud (Gian lận giao dịch)
Chuyển dịch meteor đến online banking dẫn đến surge online fraud mọi loại. Research gần đây underline severity: 33% chi phí fraud U.S banks 2021 từ online banking – tăng 26% từ 2020 (ABA Banking Journal, 2022).
Quý 1 2021, online banking chiếm 96% tất cả banking transactions, accounted for 93% fraud attempts (Security, 2021).
Nhiều financial services organization chuyển sang ML/AI technology combat fraud và strengthen data security. AI/ML models dùng sophisticated mathematical/statistical algorithms exploit patterns và derived inferences identify risks và quickly determine rank order và score relative likelihood specified outcome xảy ra. Algorithms này analyze individual components của transaction xác định probability unauthorized, fraudulent, hoặc từ stolen credit card.
AI/ML model algorithms learn mỗi iteration, bằng cách store inferences derived từ prior transactions, improve accuracy risk assessment và scoring theo thời gian. Adapt changing biometric behavior và transaction patterns handle new fraud scenarios.
Dùng AI/ML, financial institutions leverage automated transaction scoring system predict transactions, adjust credit scores, detect fraud hyper-efficiently. Real-time transaction scoring algorithms consider: transaction details, user profiles, behavioral biometrics, geolocation, IP/device metadata, user financial information, và hơn nữa.
Tuy nhiên, effectiveness của AI/ML models hinges on speed truy cập transaction data. ML algorithms make predictions từ combination data derived từ offline và online feature stores – cả hai crucial trong data pipeline architecture.
Offline feature store cho fraud detection systems chứa historical data, ví dụ cách mỗi user interact với bank account. Mỗi transaction của user broken down thành hundreds of different features tạo personal log typical behavior. Log bao gồm essential data: frequency similar transactions, requested amount, IP address location.
Patterns identified và digital profile created represent cách user interact với account. Nhưng đây static data updated periodically, insufficient cho ML models predict fraud trên transaction real-time.
Đây là lúc online feature store vào chơi. Khi user make transaction, online feature store gather real-time data across different streaming sources và compare với historical data.
ML algorithms dùng comparisons amongst hundreds of features determine inconsistencies. Nếu Ben ở Spain và purchase tại Germany 5 phút sau, ML algorithms flag potential fraud.
Toàn bộ efficacy calculations dependent trên online feature store cung cấp real-time data. Quyết định approve/reject transaction cần accurate và instantaneous shut off fraudulent activity.
Leverage online feature store giúp prevent fraud across various payment mechanisms:
- Credit và debit card payments
- Person-to-person transfers
- Bank account credits và debits
- Mobile wallets và e-payments
Know Your Customer (KYC)
Ngân hàng follow know-your-customer (KYC) regulations lâu rồi và vẫn favored method combat financial fraud. Nhưng nhiều vẫn rely knowledge-based authentication (KBA), data static không update đủ frequent reliable hoặc safe. Recent data breaches tại Equifax và Capital One gezeigt identity data có thể stolen và dùng cho fraud và account takeover.
Ngân hàng cần agile và speed để fast decisions swiftly dispel fraudulent activity. Decisions based on KBA criteria như name, address, social security gives criminals wiggle room out-maneuver bank data security systems.
Cần sophisticated technology hơn tạo powerful cybersecurity, strengthen data security systems, mitigate risk data breaches – tại sao nhiều bank turning to dynamic digital identities. Qua modern approaches, document verification và biometric records combine với intricate behavioral patterns tạo digital identity cho mỗi user.
Đặt stronger padlock trên accounts, khiến criminals khó fake/mimic digital identities. Nhưng speed vẫn crucial factor. Digital identities complex, made up nhiều sources và data types. Khó khăn update everything nhanh đủ cho banks stay ahead criminals without hamper user experience.
Thách thức hơn nữa: criminal underworld evolving cùng banks, discovering savvier ways commit fraud bằng synthetic digital identities – process blend real và fake customer information thành identity mới. Ví dụ: steal social security number dùng tạo fake date of birth hoặc home address. Financial world aware threat synthetic fraud, cost U.S. banks $20 tỷ năm 2020 (ABA Banking Journal, 2021).
Fraudsters know stay undetected bằng cách ensure all payments paid on time và build credit history avoid exhibiting risk factors. Makes detecting synthetic fraud nearly impossible cho banks. Best defense: detect tại account creation hoặc early transaction/payment process.
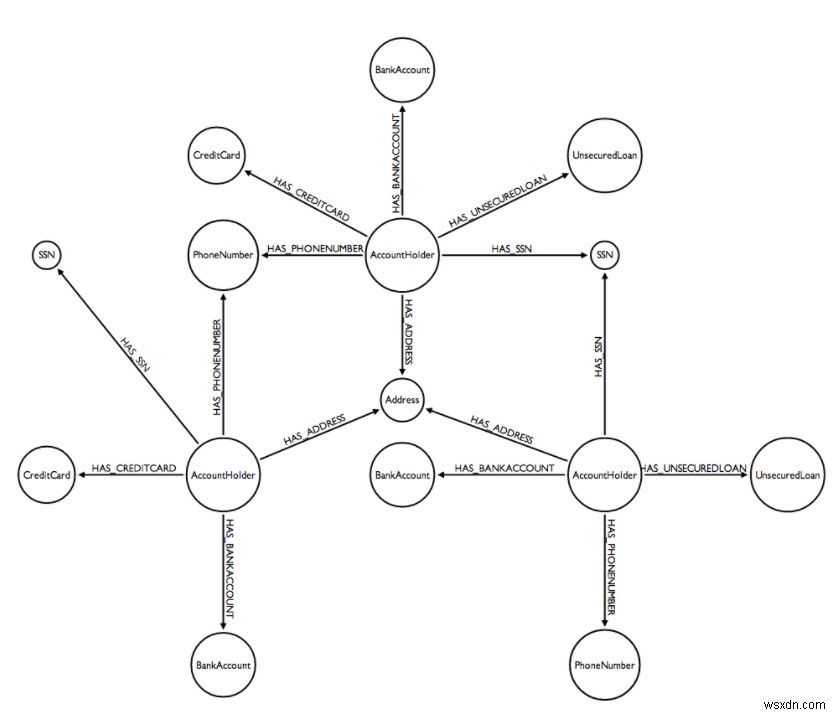
Quan trọng vì nếu criminals given enough time, họ proceed next step fraud cycle: alter fake information tạo additional digital identities. Tức formulate và create network fake identities eventually connected/shared với one or more pieces information: bank accounts, phone numbers, social security numbers, hơn nữa.
Cung cấp opportunity cho banks detect fraudulent activity bằng cách identify connections giữa personal information của user.
Solution: dùng graph database represent và store data as series of nodes và edges model relationships giữa data points. Fraud và data security analysts detect suspicious connections/patterns bằng cách traverse graph of customers (digital identities) và/hoặc transaction attributes preferably real-time.
Để stay ahead criminals, banks phải leverage low-latency in-memory multi-model databases deliver high throughput required keep digital identities updated và build identity graphs detect synthetic fraud real-time.
Real-time database này faster và flexible hơn traditional relational databases và gives banks best chance identify customers correctly và flag suspicious transactions.
Anti-Money Laundering (AML)
Dirty money cần launder và banks là favored channels criminals leverage accumulate wealth illegally. Thực tế money laundering pervasive và problematic. Dù combat plague vẫn top-tier challenge, criminals vẫn tìm cách disrupt system.
Estimated $2 trillion laundered globally mỗi năm (Deloitte, 2020) và 50% money laundering undetected across industry (Renolon, 2022). Governments tightening squeeze trên banks become more vigilant validate transactions through more stringent AML regulations.
AML-related fines getting higher recent years, total amount rising to $10.4 tỷ globally by end 2020 (Compliance Week, 2020), highlight failure financial institutions comply money laundering laws. Nhưng 62% compliance officers nói criminal activity getting harder to spot (Renolon, 2022), banks cần new innovative ways clamp down money laundering và strengthen cybersecurity.
Nhiều banks leverage AI và digital identity technologies enhance transaction monitoring systems và weed out money launderers. Network analytics, ví dụ, help identify hidden links giữa entities more likely missed traditional methods.
Linchpin của bất kỳ AML compliance program là monitoring system cung cấp transaction scoring across many variables real-time. Data cần analyze colossal, speed processed determines successfully banks identify suspicious transactions.
Ngân hàng cần Real-Time Database clamp down Fraud
Chúng ta sống fast-paced environment nơi criminals evolved discovered savvier ways steal và create fake identities commit fraud. Banks cần adapt digital age và move away từ rigid slow legacy RDBMS systems không support modern AI/ML-based fraud detection và dynamic digital identities.
Kết quả, nhiều banks turning to real-time databases become more agile, responsive, adept tackling fraud. Redis Enterprise với native modules RedisJSON, RediSearch, RedisGraph, RedisTimeSeries, RedisBloom được leverage bởi nhiều financial services firms nhờ ability efficiently process multiple data models và identify suspicious patterns.
Nó empower banks bằng cách cung cấp fraud detection platforms real-time access required quickly analyze patterns in transactions và augment KYC programs với new tools digital identity. Redis Enterprise offer financial services companies mission-critical, in-memory database với sub-millisecond performance, global scalability, 99.999% uptime, multicloud support, và hơn nữa.
Để discover thêm thông tin Redis Enterprise power real-time fraud detection, đọc whitepaper này.